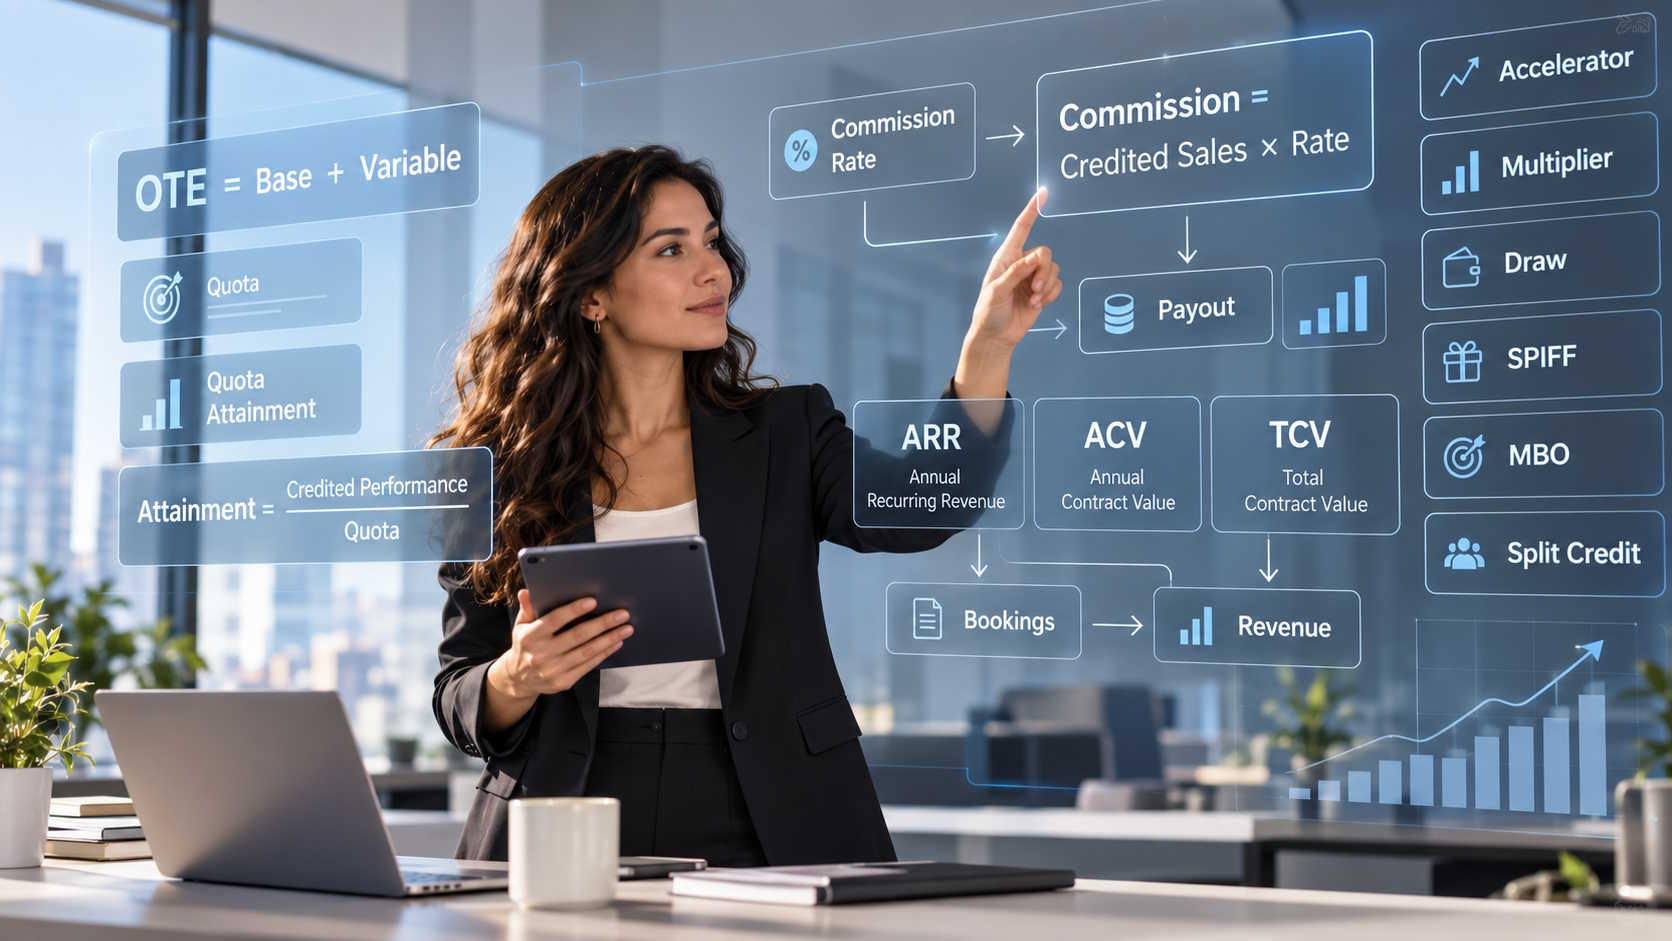
Sales compensation has its own language.
Terms such as quota attainment, OTE, commission rate, accelerator, credit, payout, and draw are used constantly—but not always consistently.
One company may call something commission credit. Another may call the same thing credited revenue. A third may simply call it bookings. Terms such as TCV, ACV, and ARR can also mean slightly different things depending on the business model and how the company measures revenue.
That creates problems.
If Finance, Sales, RevOps, and the sales compensation team use the same words to mean different things, compensation plans become harder to understand, administer, and audit.
This guide explains the most common terminology used in sales compensation, the alternative terms you may encounter, and—where applicable—the math connecting the different metrics.
The Basic Sales Compensation Equation
Before going term by term, it helps to understand the basic structure of most sales compensation plans.
At a high level:
Sales Performance → Credited Performance → Quota Attainment → Payout
For example:
- A rep closes $1.2M in credited revenue.
- Their quota is $1M.
- Their quota attainment is 120%.
- Their compensation plan determines how much commission is earned at 120% attainment.
The underlying math is:
Quota Attainment = Credited Performance ÷ Quota
So:
$1.2M ÷ $1M = 120% attainment
The next step is determining the payout associated with that attainment. Depending on the plan, this may be calculated using a commission rate, a target incentive, an attainment-to-payout curve, accelerators, tiers, bonuses, or multiple performance measures.
Understanding these relationships makes the rest of the terminology much easier.
Compensation Structure Terms
OTE — On-Target Earnings
On-Target Earnings, usually abbreviated OTE, represents how much a salesperson is expected to earn if they achieve 100% of their performance targets.
OTE normally includes:
OTE = Base Salary + Target Variable Compensation
Example:
| Component | Amount |
|---|---|
| Base Salary | $120,000 |
| Target Variable Compensation | $80,000 |
| OTE | $200,000 |
A salesperson earning exactly 100% of quota would therefore be expected to earn approximately $200,000 for the year.
Companies may also use terms such as Target Compensation, Total Target Compensation (TTC), Target Cash Compensation, or On-Target Compensation. These usually mean something similar, although companies should define whether equity, bonuses, or other compensation are included.
Base Salary
The base salary is the fixed portion of compensation paid regardless of sales performance.
For example, in a $200,000 OTE plan with $120,000 base and $80,000 variable, the rep has a 60/40 pay mix.
Variable Compensation
Variable compensation is the portion of compensation dependent on performance. It may include commissions, bonuses, SPIFFs, MBO payments, or other performance-based incentives.
For many sales roles:
Variable Compensation at Target = OTE − Base Salary
Variable compensation is sometimes called Incentive Compensation, Target Incentive, Variable Pay, or Incentive Pay.
Pay Mix
The pay mix describes the relationship between fixed and variable compensation.
For a salesperson with $120,000 base, $80,000 target variable, and $200,000 OTE, the pay mix is 60% Base / 40% Variable.
Common pay mixes include:
| Role Type | Typical Pay Mix |
|---|---|
| Enterprise Account Executive | 50/50 or 60/40 |
| Mid-Market AE | 60/40 |
| SDR / BDR | 70/30 |
| Customer Success | 70/30 or 80/20 |
Roles with greater direct influence over revenue often have more compensation at risk.
Target Incentive
The target incentive is the variable compensation a participant earns at 100% performance.
For a $200,000 OTE plan with a $120,000 base, the target incentive is $80,000. At exactly 100% quota attainment, the plan might therefore produce an $80,000 payout.
However, this is not universal. Some compensation plans contain thresholds, bonuses, multipliers, or additional measures that make the relationship more complex.
Sales Performance Terms
Quota
A quota is the performance target assigned to a salesperson, team, or territory.
Examples include:
- $1M bookings quota
- $2M ARR quota
- $3M revenue quota
- 50 qualified meetings
- $10M pipeline generation
- 100 new customers
Quota is sometimes called Target, Sales Target, Goal, or Performance Target. It does not necessarily have to be revenue-based.
Quota Attainment
Quota attainment measures performance relative to quota.
The basic formula is:
Quota Attainment = Credited Performance ÷ Quota
| Credited Sales | Quota | Attainment |
|---|---|---|
| $900,000 | $1,000,000 | 90% |
| $1,000,000 | $1,000,000 | 100% |
| $1,300,000 | $1,000,000 | 130% |
Quota attainment is one of the most important metrics in sales compensation because many plans use attainment to determine payout rates.
Sales Credit
Sales credit is the amount of performance credited toward a participant’s compensation plan.
This is important because sales credit does not always equal the underlying transaction value.
For a $100,000 deal involving two salespeople, the company might assign:
| Participant | Credit Share | Credited Amount |
|---|---|---|
| Rep A | 70% | $70,000 |
| Rep B | 30% | $30,000 |
Sales credit may also depend on product, territory, deal source, role, customer segment, revenue type, split rules, or overlay participation.
Other common terms include Credited Revenue, Commission Credit, Quota Credit, Creditable Revenue, and Eligible Revenue. These are often used interchangeably, although technically they can represent different stages of a compensation calculation.
Crediting
Crediting is the process used to determine which participants receive credit for a transaction. It answers questions such as:
- Who gets credit?
- How much credit do they receive?
- When does the credit occur?
- Which product or revenue amount is eligible?
Crediting rules are often more complex than commission formulas themselves.
Split Credit
A split occurs when multiple participants receive credit for the same transaction. For a $200,000 opportunity:
| Participant | Split | Credited Amount |
|---|---|---|
| Account Executive | 70% | $140,000 |
| Overlay Specialist | 30% | $60,000 |
Importantly, not every company requires splits to total 100%. Some organizations intentionally use overlay credit, meaning multiple participants can each receive full or partial credit.
A $100,000 transaction could therefore produce $100,000 of AE credit and $100,000 of specialist credit—creating $200,000 of compensation credit from $100,000 of actual business. This distinction matters when analyzing incentive cost.
Revenue and Transaction Terms
Bookings
Bookings generally represent the value of contracts signed during a period.
However, companies calculate bookings differently. Depending on the organization, bookings may mean total contract value, annual contract value, first-year contract value, committed subscription value, or recognized deal value.
Because bookings are frequently used for compensation, companies should explicitly define what counts.
TCV, ACV, ARR, and MRR
These four metrics are the most commonly confused in SaaS compensation. Here is how they relate on a three-year, $100,000-per-year contract:
| Metric | Definition | Value |
|---|---|---|
| TCV — Total Contract Value | Total committed value of the contract | $300,000 |
| ACV — Annual Contract Value | Annualized value of the contract | $100,000 |
| ARR — Annual Recurring Revenue | Recurring subscription revenue normalized to a year | $100,000 |
| MRR — Monthly Recurring Revenue | Monthly equivalent of recurring revenue | $8,333 |
Some useful shortcuts:
- TCV = ACV × Contract Term (when contract value is evenly distributed)
- ARR = MRR × 12
- MRR = ARR ÷ 12
ARR typically excludes one-time services or implementation fees, although exact definitions differ by company. ACV may include elements that a company does not classify as recurring revenue.
Revenue
Revenue generally refers to revenue recognized according to the company’s accounting policies. Revenue is different from bookings.
For example, a customer signs a $120,000 one-year contract. Bookings might immediately equal $120,000, but recognized revenue might be $10,000 per month.
This distinction becomes particularly important when compensation plans pay based on recognized revenue or consumption instead of contract bookings.
Consumption
Consumption measures how much of a product or service a customer actually uses. This has become increasingly relevant for companies with usage-based pricing models.
If a customer commits to $500,000 but consumes only $350,000:
- A traditional bookings-based model might pay the rep on $500,000.
- A consumption-based model might pay the rep on $350,000.
Some plans combine both.
Commission Calculation Terms
Commission Rate
A commission rate determines how much compensation is earned per unit of credited performance.
The simplest formula is:
Commission = Credited Sales × Commission Rate
Example: $500,000 credited sales × 8% commission rate = $40,000.
Base Commission Rate
The base commission rate is usually the commission rate associated with performance before accelerators or other modifiers.
In quota-based plans, it can often be derived from:
Base Commission Rate = Target Incentive ÷ Quota
Example: $100,000 target incentive ÷ $1,000,000 quota = 10% base rate. If the plan is perfectly linear, producing $1M in credited sales would generate $100,000 of commission.
Payout
Payout is the compensation amount earned under the plan. A payout may be calculated from revenue, attainment, commission rates, bonus schedules, scorecards, multipliers, or multiple plan components.
“Payout” and “commission” are sometimes used interchangeably, although payout is generally the broader term.
Payout Percentage
A payout percentage often represents variable compensation earned relative to target incentive.
Payout Percentage = Actual Incentive Earned ÷ Target Incentive
Importantly, payout % does not necessarily equal quota attainment %. At 120% quota attainment, a rep might receive 140% of target incentive because of accelerators.
Accelerator and Tier Terms
Accelerator
An accelerator increases the commission rate once a salesperson reaches a particular performance level.
| Attainment | Commission Rate |
|---|---|
| 0 – 100% | 8% |
| 100 – 125% | 12% |
| Above 125% | 16% |
A rep who exceeds quota therefore receives a higher rate on incremental sales. Accelerators are designed to make additional performance increasingly valuable to the salesperson.
Decelerator
A decelerator reduces the payout rate at lower levels of performance.
| Attainment | Rate |
|---|---|
| 0 – 50% | 4% |
| 50 – 100% | 8% |
| Above 100% | 12% |
Companies use decelerators to limit incentive payments for underperformance.
Tier
A tier is a performance range associated with a particular payout rule. For example: 0–75%, 75–100%, 100–125%, and above 125%. Each tier may have a different commission rate.
Marginal or Incremental Rate
A marginal rate applies only to performance within a particular tier.
Consider a plan with 10% for 0–100% attainment and 15% above 100%. If quota is $1M and a rep sells $1.2M:
| Tier | Sales in Tier | Rate | Commission |
|---|---|---|---|
| First $1.0M | $1,000,000 | 10% | $100,000 |
| Above quota | $200,000 | 15% | $30,000 |
| Total | $130,000 |
This is often called a marginal, incremental, or tiered accelerator.
Retroactive Accelerator
A retroactive accelerator applies the higher rate to earlier performance once a threshold is achieved.
Using the previous example (10% up to 100%, 15% at 120% attainment retroactively), if the rep reaches $1.2M, the company might apply 15% to the entire amount:
$1.2M × 15% = $180,000
This produces a dramatically different result from a marginal accelerator. Because of that, compensation plans should clearly specify whether tiers are incremental or retroactive.
Multiplier
A multiplier adjusts a payout or commission rate. For example, a $20,000 base commission with a 1.25× strategic product multiplier yields $25,000.
Multipliers may be based on product, customer type, contract length, margin, strategic priority, or performance level.
Thresholds, Caps, and Limits
Threshold
A threshold is the minimum performance required before compensation begins. For example: no commission below 50% attainment.
Once the salesperson crosses the threshold, the plan may pay only on performance above the threshold, retroactively from the first dollar, or based on a predefined payout curve. These approaches produce very different economics.
Cap
A cap places a maximum limit on compensation. For example, a maximum annual variable compensation of $300,000 means even if the calculated commission is $400,000, payout is limited to $300,000.
Some plans use caps only on specific components rather than total compensation.
Uncapped Commission
An uncapped plan has no predetermined maximum payout. Many sales organizations favor uncapped plans because they maintain incentives for exceptional performance.
Bonus Terminology
Bonus
A bonus is a fixed or formula-based payment tied to achieving a defined objective. For example: close five new enterprise customers for a $10,000 bonus. Unlike a commission rate, the bonus may not increase proportionally with transaction value.
SPIFF
SPIFF generally refers to a short-term sales incentive used to encourage a specific behavior. Examples include:
- $500 for selling a particular product
- $1,000 for closing a deal before quarter-end
- Extra 2% commission on a new product
- $250 per qualified meeting during a campaign
SPIFF may also be written as SPIF, Sales Performance Incentive Fund, or Sales Promotion Incentive Fund. The historical expansion of the acronym is less important than its practical meaning: a temporary incentive layered on top of the core compensation plan.
MBO — Management by Objectives
An MBO is compensation based on achieving predefined objectives rather than directly on a sales transaction.
Example: a $20,000 quarterly target incentive weighted across three objectives:
| Objective | Weight |
|---|---|
| 40% product adoption | 40% |
| 30% strategic accounts | 30% |
| 30% pipeline quality | 30% |
The final MBO payout is typically based on a weighted score.
Draws and Guarantees
Draw
A draw provides a salesperson with compensation before sufficient commissions have been earned. Draws are frequently used during ramp periods. There are two major types.
Recoverable Draw
A recoverable draw is effectively an advance against future commissions.
| Month | Draw Paid | Commission Earned | Recoverable Balance |
|---|---|---|---|
| Month 1 | $5,000 | $3,000 | $2,000 |
Future commissions may be reduced until the $2,000 balance has been repaid.
Non-Recoverable Draw
A non-recoverable draw guarantees a minimum incentive payment without requiring repayment.
If the guaranteed draw is $5,000 and earned commission is $3,000, the salesperson receives $5,000. The $2,000 difference does not need to be repaid.
Guarantee
A guarantee is a predetermined minimum payment, commonly used for new hires or employees transitioning between territories or plans. Companies sometimes use “guarantee” and “non-recoverable draw” interchangeably.
Ramp Terminology
Ramp
A ramp period is the period during which a new salesperson gradually moves toward full productivity. Companies may modify quota, commission rates, guarantees, draws, or targets during this period. Ramp plans are common but need to be designed carefully.
Example ramp against a $100,000 annualized monthly quota:
| Month | Ramp % | Monthly Quota |
|---|---|---|
| Month 1 | 25% | $25,000 |
| Month 2 | 50% | $50,000 |
| Month 3 | 75% | $75,000 |
| Month 4+ | 100% | $100,000 |
Prorated Quota
A prorated quota adjusts the quota based on how much of the period a salesperson was active.
Example: an annual quota of $1.2M with a rep starting July 1 and six months remaining produces a $600,000 prorated quota. Ramp schedules may reduce the target further.
Timing Terms
Performance Period
The performance period is the period over which performance is measured—monthly, quarterly, semiannual, or annual. A salesperson might have an annual quota while commissions are calculated monthly.
Commission Period
The commission period is the period used to calculate compensation. For example, sales quota may be annual, commission calculations monthly, and payroll monthly. These periods do not necessarily need to match.
Credit Date
The credit date determines which compensation period receives credit for a transaction. Possible credit dates include:
- Opportunity close date
- Contract signature date
- Booking date
- Invoice date
- Payment date
- Revenue recognition date
This is one of the most important definitions in a compensation plan because changing the credit date can shift performance between periods.
Payment and Accounting Terms
Earned Commission
Earned commission generally refers to commission that has met the conditions required to be considered earned under the compensation plan. Those conditions might include contract signature, customer payment, completion of a cancellation period, delivery, or revenue recognition.
Companies should define this carefully because “calculated,” “earned,” and “paid” commissions may occur at different times.
Paid Commission
Paid commission is compensation that has actually been processed through payroll or another payment system.
Therefore:
Calculated Commission ≠ Earned Commission ≠ Paid Commission
at every point in time. A transaction may have a calculated commission of $10,000 today but not be paid until next month’s payroll.
Accrued Commission
An accrued commission is a commission expense that the company expects to owe but has not yet paid. This term is particularly relevant to Finance and Accounting.
Adjustments and Exceptions
Adjustment
An adjustment changes a previously calculated compensation amount. Examples include correcting transaction data, reassigning sales credit, applying an exception, reversing an incorrect payment, correcting quota, or adjusting commission after a deal change.
Adjustments should ideally reference the original transaction so an auditor can trace exactly why compensation changed.
Manual Adjustment
A manual adjustment is an administrator-entered change not automatically generated from a source transaction—for example, a +$1,000 bonus, a −$500 correction, or a +$5,000 management-approved payment.
Manual adjustments are common but should be tightly controlled and documented.
True-Up
A true-up reconciles previously calculated compensation with the amount that should ultimately have been paid.
If estimated commission was $8,000 and the final commission is $9,500, the true-up is +$1,500.
True-ups frequently occur with consumption plans, revenue recognition, quarterly bonuses, annual compensation calculations, or data arriving after payroll closes.
Clawback
A clawback reverses compensation previously credited or paid. Common triggers include customer cancellation, non-payment, refund, contract reduction, or deal reversal.
Example: an original commission of $10,000 on a deal where the customer later cancels half the contract could produce a $5,000 clawback.
Some companies distinguish between a clawback, which recovers previously paid money, and a reversal, which removes a commission before it is paid. Either way, how you handle clawbacks has a real impact on rep trust.
Plan Design Terms
Component
A component is an individual portion of a compensation plan. A plan might include 70% ARR attainment, 20% new logo performance, and 10% strategic product objective. Each component may have its own quota, crediting rules, and payout curve.
Weight
A weight specifies how much of target incentive is associated with a component.
| Component | Weight | Target Incentive |
|---|---|---|
| Revenue | 70% | $70,000 |
| New Customers | 20% | $20,000 |
| MBO | 10% | $10,000 |
| Total | 100% | $100,000 |
Scorecard
A scorecard combines multiple performance measures into a single incentive structure.
| Metric | Weight |
|---|---|
| Revenue | 50% |
| New Customers | 30% |
| Retention | 20% |
Each metric produces a payout that is multiplied by its weight.
Territory and Participant Terminology
Participant
A participant is a person participating in a compensation plan. This is often synonymous with Sales Rep, Payee, Employee, Seller, or Plan Participant.
“Participant” is broader because compensation systems may include managers, overlays, customer success employees, or other nontraditional sales roles.
Territory
A territory defines the customers, prospects, geography, products, or accounts assigned to a salesperson. Territories can be based on geography, account, industry, customer size, product, named accounts, or combinations of these dimensions. Territory assignment frequently determines compensation credit.
Overlay
An overlay is a salesperson who supports transactions without necessarily owning the primary customer relationship. Examples include product specialists, solution specialists, sales engineers, and strategic account overlays.
Overlay compensation may involve independent credit rather than splitting the primary salesperson’s credit.
Plan Governance Terms
Compensation Plan
A compensation plan defines performance measures, quotas, crediting rules, commission rates, accelerators, thresholds, caps, bonuses, and payment rules. It is effectively the rulebook describing how sales performance becomes compensation.
Plan Document
The plan document is the formal documentation communicating the compensation plan to the salesperson. It often includes OTE, quota, performance measures, rates, terms, payment timing, clawback policies, and eligibility rules.
Plan Version
A plan version represents the set of compensation rules effective during a particular period.
For example, January 1 – June 30 might have one accelerator structure, while July 1 – December 31 uses another.
This matters because historical compensation should generally be calculated using the plan configuration that was effective when the transaction occurred—not simply today’s plan configuration.
Effective Date
The effective date determines when a compensation rule becomes active. Effective dating may apply to quotas, rates, territory assignments, participant assignments, plan versions, and accelerator tables.
Without effective dates, reconstructing historical compensation becomes extremely difficult.
Putting It All Together
Consider an Account Executive with:
| Plan Attribute | Value |
|---|---|
| OTE | $200,000 |
| Base Salary | $100,000 |
| Target Incentive | $100,000 |
| Annual Quota | $1,000,000 |
Their base commission rate is:
$100,000 ÷ $1,000,000 = 10%
Suppose the plan pays:
| Attainment | Rate |
|---|---|
| 0 – 100% | 10% |
| 100 – 125% | 15% |
| Above 125% | 20% |
The rep generates $1,400,000 of credited revenue, so quota attainment is 140%.
Commission then becomes:
| Tier | Sales in Tier | Rate | Commission |
|---|---|---|---|
| First $1.0M | $1,000,000 | 10% | $100,000 |
| $1.0M – $1.25M | $250,000 | 15% | $37,500 |
| Above $1.25M | $150,000 | 20% | $30,000 |
| Total Incentive | $167,500 |
Total cash compensation:
$100,000 Base + $167,500 Variable = $267,500
This relatively simple example ties together OTE, base salary, target incentive, quota, credited revenue, attainment, commission rate, accelerators, and payout.
In real organizations, additional complexity can come from splits, product multipliers, SPIFFs, ramp schedules, draws, clawbacks, multiple plan components, and retroactive transaction changes.
Why Terminology Matters
Sales compensation terminology is not just semantics.
A compensation plan is ultimately a set of mathematical and business rules. Small differences in definitions can materially change payouts.
Consider questions such as:
- Does “revenue” mean bookings, ARR, or recognized revenue?
- Does an accelerator apply incrementally or retroactively?
- Does a split reduce another participant’s credit?
- Is quota attainment based on gross sales or credited sales?
- Is a customer cancellation a reversal or clawback?
- Does a quota change apply retroactively?
- Is payout calculated monthly or cumulatively for the year?
Without precise definitions, two people can read the same compensation plan and calculate two different answers.
The best compensation programs therefore treat terminology as part of the plan architecture itself. Every major metric should have:
- A precise definition
- A calculation formula
- A source of data
- An effective date
- A clearly defined relationship with the other metrics in the plan
That creates a compensation system that is easier for sellers to understand, easier for RevOps to administer, and easier for Finance to audit.
Frequently Asked Questions
What is the difference between quota and quota attainment?
Quota is the performance target. Quota attainment measures actual credited performance relative to that target.
Attainment = Performance ÷ Quota
What is the difference between OTE and target incentive?
OTE includes both base salary and target variable compensation:
OTE = Base Salary + Target Incentive
Target incentive represents only the variable portion expected at target performance.
What is the difference between bookings and revenue?
Bookings generally represent contracts signed, while revenue generally represents the portion recognized for accounting purposes. The exact definition varies by company.
What is the difference between ARR and ACV?
ARR measures annual recurring revenue. ACV measures the annualized value of a contract and may include elements that a company does not classify as recurring revenue.
In many subscription businesses they can be similar, but they should not automatically be assumed to be identical.
What is the difference between sales credit and transaction value?
Transaction value describes the underlying business transaction. Sales credit describes how much of that transaction is credited to a participant for compensation purposes.
A $100,000 transaction might therefore generate $50,000, $100,000, or even more than $100,000 of compensation credit depending on the company’s crediting rules.
What is the difference between an accelerator and a multiplier?
An accelerator typically increases payout as performance crosses an attainment threshold. A multiplier modifies compensation based on another condition, such as product type or strategic priority.
What is the difference between commission and payout?
Commission usually refers to compensation calculated from sales activity. Payout is broader and can include commissions, bonuses, MBOs, SPIFFs, and other incentive components.
Why do companies use different sales compensation terminology?
Sales compensation sits at the intersection of Sales, Finance, HR, Accounting, and Revenue Operations. Each function brings its own terminology.
Business models also differ. A SaaS company may focus on ARR. A consumption company may focus on usage. A services organization may compensate on recognized revenue or gross margin.
For that reason, there is no universal sales compensation vocabulary. The important thing is not necessarily which term a company chooses—it is that everyone agrees on exactly what the term means and how it is calculated.
About the author
Jose Fernandez is part of the team behind EasyComp.ai, building infrastructure that helps companies run sales compensation without spreadsheets, confusion, or delays. He believes incentive systems should be easy to operate—and crystal clear to the people who earn them.